Specialty
Retirement planning: questions for an advisor
Learn what to ask about retirement planning and review topic-tagged advisor profiles. Verify each advisor's experience, registration, fees and fit.
Begin with the retirement you need to fund
Retirement planning is not one target balance. It is a sequence of decisions about when income stops, what spending remains, which income sources start when, and how much uncertainty the plan can bear. Separate essential spending from flexible spending and one-time costs. Add housing, health care, family support and taxes. An advisor should show a year-by-year cash-flow view and explain what changes when one spouse retires before the other or lives much longer. A single calculator output can start a conversation, but it cannot replace that work.

Know which income is dependable and which is variable
List Social Security, pensions, annuities, part-time work and portfolio withdrawals separately. Social Security claiming affects the monthly benefit and can affect survivor income; get current estimates from SSA's retirement planner. A pension may offer a lump sum, lifetime payments or survivor options. Compare these using actual plan terms, inflation exposure, tax treatment and the needs of both spouses before making an irreversible election. The investment portfolio then has a clearer job: cover gaps, absorb surprises and preserve longer-term purchasing power.
Ask an advisor to illustrate low-return and high-inflation periods, not only an average market. Losses early in retirement while withdrawing can shrink the capital available for recovery. A cash or short-term bond reserve may help meet immediate spending, but a reserve that is too large may lose purchasing power. The right balance depends on guaranteed income, flexibility and risk tolerance.
Coordinate taxes across account types
Withdrawals from taxable, traditional tax-deferred and Roth accounts have different effects. A Roth conversion can increase current tax and sometimes Medicare-related costs while reducing future traditional-account balances. Required minimum distributions depend on the account and birth year; check the IRS's current RMD guidance. Ask who prepares annual tax projections, who works with your CPA, and how the plan changes after a spouse dies. Do not choose a conversion or withdrawal order from a generic article.
Stress-test health and longevity
Compare current insurance and Medicare costs from Medicare's current cost page. Ask what the plan assumes for premiums, out-of-pocket care, long-term care, housing changes and help for relatives. A plan that works only if both people die at average life expectancy is not a resilient plan. An advisor should show what can be adjusted if costs rise, and coordinate estate-document questions with an attorney rather than drafting them.

Watch for decisions that cannot easily be undone
A pension election, annuity purchase and Social Security claim can affect income for decades. Before selecting a lump sum, ask whether the plan provides a survivor benefit, whether payments adjust for inflation, and what happens if the employer plan or insurer fails. Compare offers in the same after-tax dollars and assumptions. A rollover may preserve control but transfers investment and longevity risk to your household. Ask for a side-by-side decision sheet, not a one-number recommendation.
Retirement timing can also determine health coverage. A person leaving work before Medicare eligibility may need a bridge, while someone enrolling in Medicare must understand enrollment windows and how other coverage interacts. Verify current costs and enrollment rules with Medicare and a benefits specialist rather than a static projection. If one spouse is younger, run separate dates for each person's coverage.
Demand an action plan, not just a Monte Carlo score
Ask for a baseline annual spending and withdrawal table, plus at least a bad-early-market case, higher health costs and a longer lifespan. The output should say what you would do: delay a large purchase, change withdrawals, rebalance, or revisit work. Specify which spending is discretionary and which is not. Update the model when actual market returns or household facts depart from assumptions; a high probability generated today is not a warranty for tomorrow.
Understand the fee and scope
Some planners charge hourly or a flat project fee; others bill ongoing asset-based fees or receive insurance compensation. The right arrangement depends on whether you want a one-time second opinion, an annual tax-aware withdrawal plan or delegated investment management. Ask for the first-year and ongoing cost in dollars, what investment fund charges add, and whether the planner will work with accounts they do not manage. A recommendation for an annuity or rollover deserves a clear comparison against keeping current benefits and accounts.
Ask how often the plan is revised, who meets with a surviving spouse, and whether you will receive a written action list after each review. "Financial planning" on a proposal is not the same as a deliverable. The advisor should spell out when the Social Security choice is revisited, when actual spending is reconciled, and who coordinates with tax and estate professionals.

Use the first meeting to test the service
- Can I see a sample annual withdrawal plan with account types, taxes and spending flexibility?
- How do you model Social Security and pension choices for both spouses?
- What action changes after a prolonged bear market or a health shock?
- Who updates the model, how often and at what total annual cost in dollars?
- How do you coordinate tax and estate issues with licensed specialists?
Check registration, fees, conflicts and disclosures through Investor.gov's IAPD guide. Unlike most directory topics here, a retirement-tagged advisor appears in this roster; a tag is not a guarantee of fit, service or outcome. Compare the work and fee, and use the related retirement calculators for illustrations.
Review advisor profiles
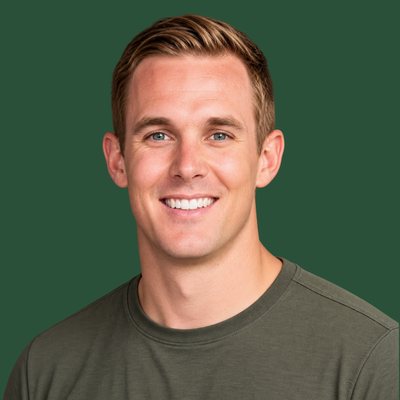
James Conole, CFP®
Founder · Root Financial
Works with people who are within about ten years of retirement and want a clear plan for getting there.
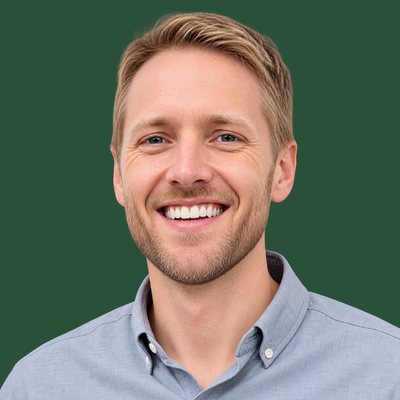
Kevin Lum, CFP®
Foundry Financial
Host of Retirement Made Simple, focused on making retirement decisions clear and straightforward.
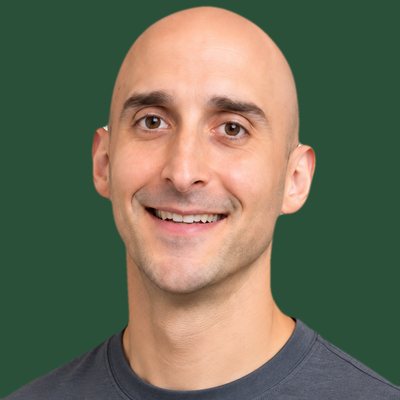
Eric, CFP®
The PeakFP
A CERTIFIED FINANCIAL PLANNER™ professional specializing in retirement income planning.
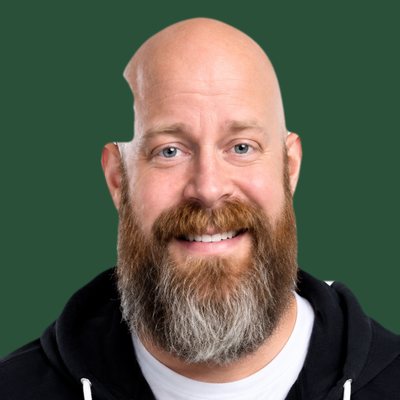
Even Better Retirement
Retirement planning
“You saved money for a lifetime, now it’s time to have fun.”
Related tools
Retirement calculatorsCommon questions
When should I start working with a retirement planning advisor?
The highest-value moments are the five to ten years before retirement and the first few years after: that's when withdrawal strategy, Social Security timing, Roth conversions, and healthcare costs get locked in. Earlier is still useful, but the stakes concentrate around the transition.
What does a retirement plan from an advisor include?
A projection of spending against income sources, a sustainable withdrawal rate, a Social Security and pension claiming strategy, tax planning across account types (traditional, Roth, taxable), Medicare and healthcare cost estimates, and a plan for the order you draw accounts down.
How much can I safely withdraw in retirement?
The 4% rule is a starting point from 1990s research, not a guarantee. Your sustainable rate depends on your asset allocation, flexibility to adjust spending, other income sources, and the returns sequence you actually experience. An advisor stress-tests your specific plan rather than quoting a single number.
What's the difference between a Roth conversion and a regular withdrawal?
A Roth conversion moves money from a traditional IRA to a Roth IRA: you pay income tax on the converted amount now, and qualified withdrawals later are tax-free. Conversions can make sense in low-income years, especially between retirement and required minimum distributions, but the right amount depends on your tax bracket each year.
Do I need a retirement advisor if I already have a 401(k)?
A 401(k) is an account, not a plan. It doesn't decide when you can retire, how much you can spend, when to claim Social Security, or how to turn savings into income. An advisor coordinates those decisions, of which the 401(k) is just one input.
Let's build a
financial life
that feels like yours.
Answer a few questions to find advisors who match your needs.